The Invisible War: How India’s Retail Traders Lost $33 Billion to Machines They Never Saw
An empirical investigation into how 8 million Indian retail traders lost over $33 billion in the options market to high-frequency trading algorithms, SEBI's probe into Jane Street, and the structural reality of modern market mechanics.
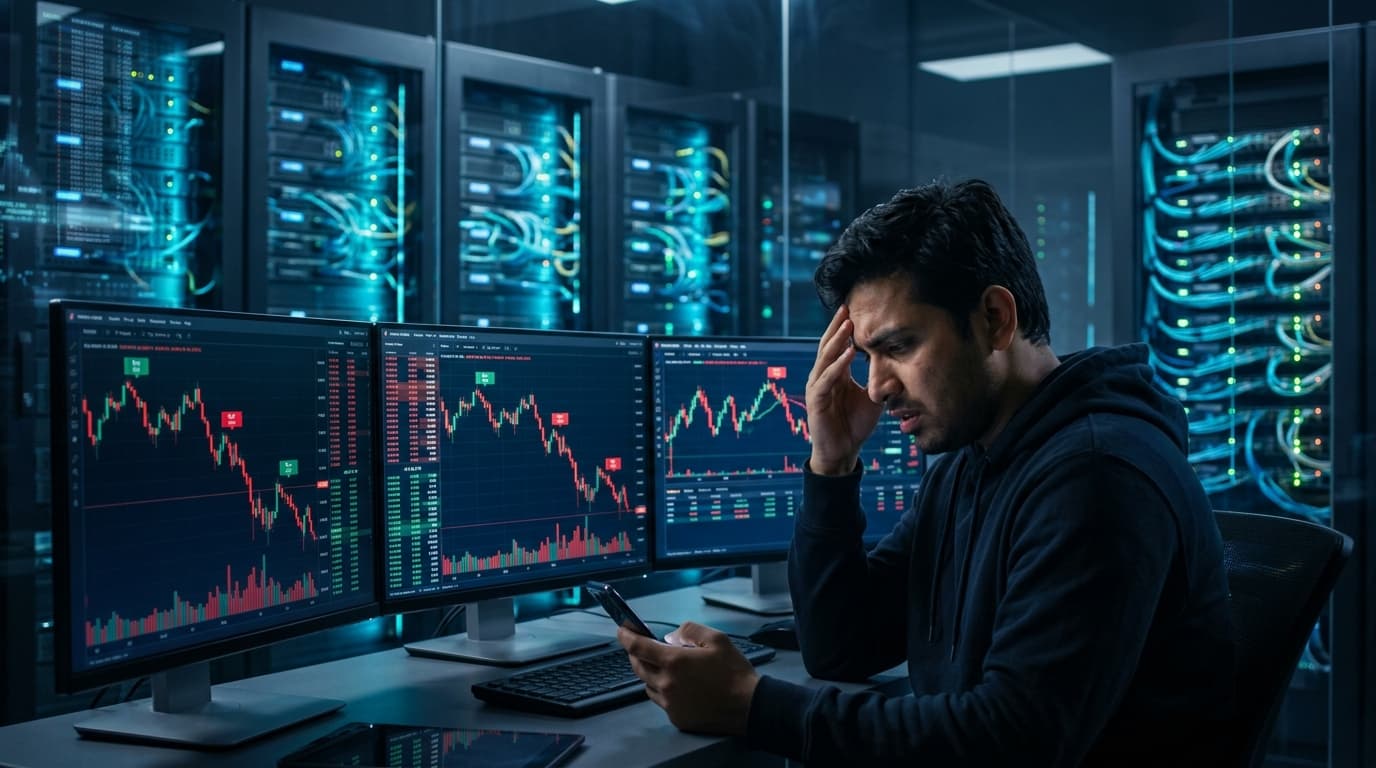
In a modest high-rise apartment in Pune, the ambient hum of midnight traffic is drowned out by the rhythmic tapping of thumbs against glass. The coffee in the ceramic mug has turned cold. On the screen of a mid-range Android smartphone, a chart flashes brilliant emerald green. A 26-year-old software engineer has just closed a Bank Nifty 48,000 Call option. The trade lasted four minutes; the net profit reads ₹8,400. For a young professional earning ₹65,000 a month, that four-minute windfall feels like a revelation.
To him, the mechanics seem simple. On YouTube and Instagram, charismatic financial influencers with millions of subscribers repeat the gospel of modern retail trading: Why wait forty years for mutual funds to compound at 12% when volatility can double your money by 3:30 PM? The derivative contracts are accessible, requiring as little as ₹2,000 to enter. The trade is executed with a casual swipe. He feels as though he has cracked an invisible code, unlocking a democratized money engine that his parents’ generation never understood.
What our trader cannot comprehend is that the transaction he just completed was not an even match between human intuition and economic momentum. He did not buy that contract from an equally optimistic retail trader in Bengaluru or Delhi. He was standing on the frontline of an invisible war—transacting against automated, water-cooled server stacks executing decisions at sub-nanosecond speeds inside fortified exchange data centers. He had stepped into a mathematical meat grinder engineered by the world’s most sophisticated quantitative trading minds.
#Markets That Move Faster Than Thought: Enter the High-Frequency Titans
The romanticized image of stock trading—men in brightly colored jackets screaming over paper slips in open-outcry pits—has been dead for a generation. Modern financial markets are silent, cold, and entirely automated. More than 75% of global turnover is governed by quantitative algorithms, driven by firms whose names rarely appear in mainstream headlines: Jane Street, Citadel Securities, Jump Trading, Tower Research, and Hudson River Trading.
+----------------------------------------------------------------------------------+
|                           THE EXECUTION GAP (LATENCY)                            |
+----------------------------------------------------------------------------------+
| Human Visual Reaction: ~200,000,000 Nanoseconds (200 ms)                         |
| Mobile 5G Order Transit: ~50,000,000 Nanoseconds (50 ms)                         |
| Fiber-Optic City Ping:  ~5,000,000 Nanoseconds (5 ms)                           |
| HFT Colocated Server:   ~350 Nanoseconds (0.00035 ms)                            |
+----------------------------------------------------------------------------------+
These institutions do not employ economic forecasters, political pundits, or stock-pickers. They employ Olympic gold-medalist mathematicians, particle physicists, and low-level computer engineers who write code in optimized C++ and burn logic directly onto custom Field Programmable Gate Arrays (FPGAs). Their edge is not visionary foresight; it is pure speed, colossal capital, and structural positioning.
#The Mumbai Fruit Bazaar: Understanding Arbitrage
Imagine the bustling Crawford Market in South Mumbai. Two fruit vendors are situated fifty meters apart: Vendor A has an oversupply of Nagpur oranges and prices them at ₹100 per kilo. Vendor B, catering to hurried shoppers near the market gate, sells the same oranges at ₹110 per kilo. An alert, agile merchant spots this ₹10 pricing inefficiency. He rushes to Vendor A, purchases 500 kilos at ₹100, and immediately walks over to Vendor B's stall, selling them to buyers for ₹109.90. His purchases at Vendor A pull the price up toward ₹104; his sales at Vendor B pull the price down toward ₹106. The market settles into a unified price equilibrium, and the swift merchant pockets a risk-free margin of ₹5 per kilo. This is classic arbitrage—the bedrock of market liquidity.
In modern capital markets, the 'oranges' are equities, index futures, and options contracts. Quantitative firms do not hold stocks hoping they will rise over a decade. They position their physical hardware in the exchange’s colocation facility—inside the exact same building as the National Stock Exchange (NSE) matching engines. While a retail trader’s order travels over cellular towers, home broadband, broker firewalls, and clearing networks—a grueling journey of 150 to 400 milliseconds—an HFT algorithm identifies pricing discrepancies between the Nifty cash index and its derivative options chain, submits the order, captures the profit, and cancels residual quotes in 350 nanoseconds.
#India’s Options Fever: A Structural Trap
How did an emerging market become the undisputed world capital of derivative speculation? Between 2019 and 2025, active individual derivative traders skyrocketed from under one million to more than eight million. India’s National Stock Exchange surpassed the US-based CME and CBOE to become the largest derivatives exchange on earth by contract volume, accounting for more than 70% of all equity derivatives traded globally.
Yet the math behind this volume was devastatingly toxic. Options contracts are wasting assets. Their value is governed by theta—the mathematical quantification of time decay. Every minute a retail trader holds an Out-of-the-Money (OTM) option without a dramatic move in the underlying asset, that contract is bleeding value directly into the hands of the entity that sold it. Retail traders, operating on limited capital, predominantly bought these low-priced OTM options because they were 'cheap,' failing to realize that an option with a 95% probability of expiring worthless is an unhedged ticket in a game with negative mathematical expectation.
#The $33 Billion Collision & The Jane Street Controversy
In late 2024, the Securities and Exchange Board of India (SEBI) published a landmark empirical study that sent shockwaves through the country's financial establishment. Between April 2021 and March 2025, Indian retail day traders logged cumulative net losses surpassing $33 billion (₹2.75 lakh crore). In the single fiscal year ending March 2024, retail traders surrendered ₹52,400 crore ($6.3 billion) to the market. Crucially, 93% of all individual traders lost money, averaging net losses of ₹1.2 lakh each, while spending an additional 25% of their principal capital on exchange levies, brokerage fees, and stamp duties. On the other side of that ledger, a small cadre of algorithmic proprietary trading houses and foreign portfolio investors extracted $7 billion (₹58,000 crore) in gross options profits over the exact same period.
| Parameter | Retail Day Traders | High-Frequency Trading (HFT) Firms |
|---|---|---|
| Execution Latency | 150 – 500 Milliseconds (Internet/Mobile) | 300 – 600 Nanoseconds (Colocation/FPGA) |
| Information Edge | Technical charts, Lagging indicators, Finfluencers | Real-time order book tick feeds, Cross-asset engines |
| Asset Strategy | Net Buyers of Out-of-the-Money (OTM) Options | Systematic Option Writers & Delta-Neutral Arbitrageurs |
| Cost of Capital | Personal savings, Personal loans, Margin leverage | Sub-1% institutional funding lines, Deep balance sheets |
| Profit/Loss Reality | 93% Net Loss Rate (Cumulative $33B lost) | Near-zero unprofitable trading days ($7B gross profit FY24) |
As the scale of retail devastation became undeniable, SEBI initiated extensive regulatory inquiries into algorithmic powerhouses, focusing intense scrutiny on Jane Street, one of the most profitable quantitative trading entities in history. Regulators observed instances where algorithmic firms acquired massive, concentrated volumes of specific heavyweight cash-market equities (such as HDFC Bank or Reliance Industries) within narrow trading windows, while simultaneously holding immense, highly leveraged put-option positions or short index futures contracts in the derivatives segment. By releasing the underlying cash-market equities during illiquid afternoon sessions, the cash index could be pulled down sharply, triggering stop-loss liquidations across millions of retail option traders and driving the opposing derivative positions into explosive multi-crore profits.
#What Ordinary Investors Must Learn
The lesson of India’s $33 billion derivatives bloodbath is cold, empirical, and uncompromising: retail day-trading against automated algorithms is not an investment strategy. It is financial suicide disguised as financial empowerment. The high-frequency machines do not get tired. They do not experience fear when an index plummets 500 points. They do not experience greed when a call option doubles. They do not read sensationalist headlines, consult astrologers, or subscribe to paid Telegram signal channels. They execute statistical probabilities millions of times per hour, governed by the cold laws of numbers and physics. Real wealth is not mined in the three-minute fluctuations of an expiry-day contract. It is accumulated along the unglamorous, patient path that algorithms cannot disrupt: owning high-quality, cash-generating businesses, holding them across economic cycles, ignoring the manufactured volatility of intraday matching engines, and letting compound interest do the heavy lifting over decades.
Yash Jondhale is the founder, owner, and editor-in-chief of BlueCreast. He authors and directs all investigative reporting, empirical analysis, and editorial coverage across Technology, Financial Markets, Geopolitics, Health, and Modern Living.
BlueCreast enforces a moderated, high-signal comment policy. Share your perspective, constructive critique, or technical observations.
Related Analyses in Finance & Wealth
America Buying Russian Diesel: Why the Policy Shift Reshapes Global Energy Markets
Washington's decision to permit 300,000 metric tons of Russian diesel reveals the tension between domestic inflation and foreign sanctions, reshaping global refining economics and India's trade positioning.

Smart Wealth Building in India: A Masterclass in Mutual Funds, SGBs, and Tax-Loss Harvesting
Demystifying modern personal finance for Indian salaried professionals and entrepreneurs. How to balance active equity, index SIPs, and sovereign gold while navigating revised capital gains rules.

RBI's Digital Rupee (e₹) Explained: How Retail CBDC and UPI Interoperability Transform Payments
Everything you need to know about the Reserve Bank of India's Central Bank Digital Currency. We demystify offline transactions, privacy guarantees, and how QR interoperability merges e₹ with UPI.
Sharp analysis delivered to your inbox every Sunday morning.
Join 25,000+ engineers, founders, and curious minds. Curated deep-dives across tech, financial independence, and high-performance living. Zero spam, unsubscribe anytime.
Double opt-in compliant. Protected by India DPDP Act and GDPR standards.